Residential appraisals across Middle Tennessee and Southern Kentucky
A residential appraisal is a licensed appraiser's independent, documented opinion of what a home is worth, based on an analysis of the property itself and the local market. Unlike an online estimate or an agent's opinion, it is developed by a professional with no financial interest in the outcome and delivered in a written report you can share with others.
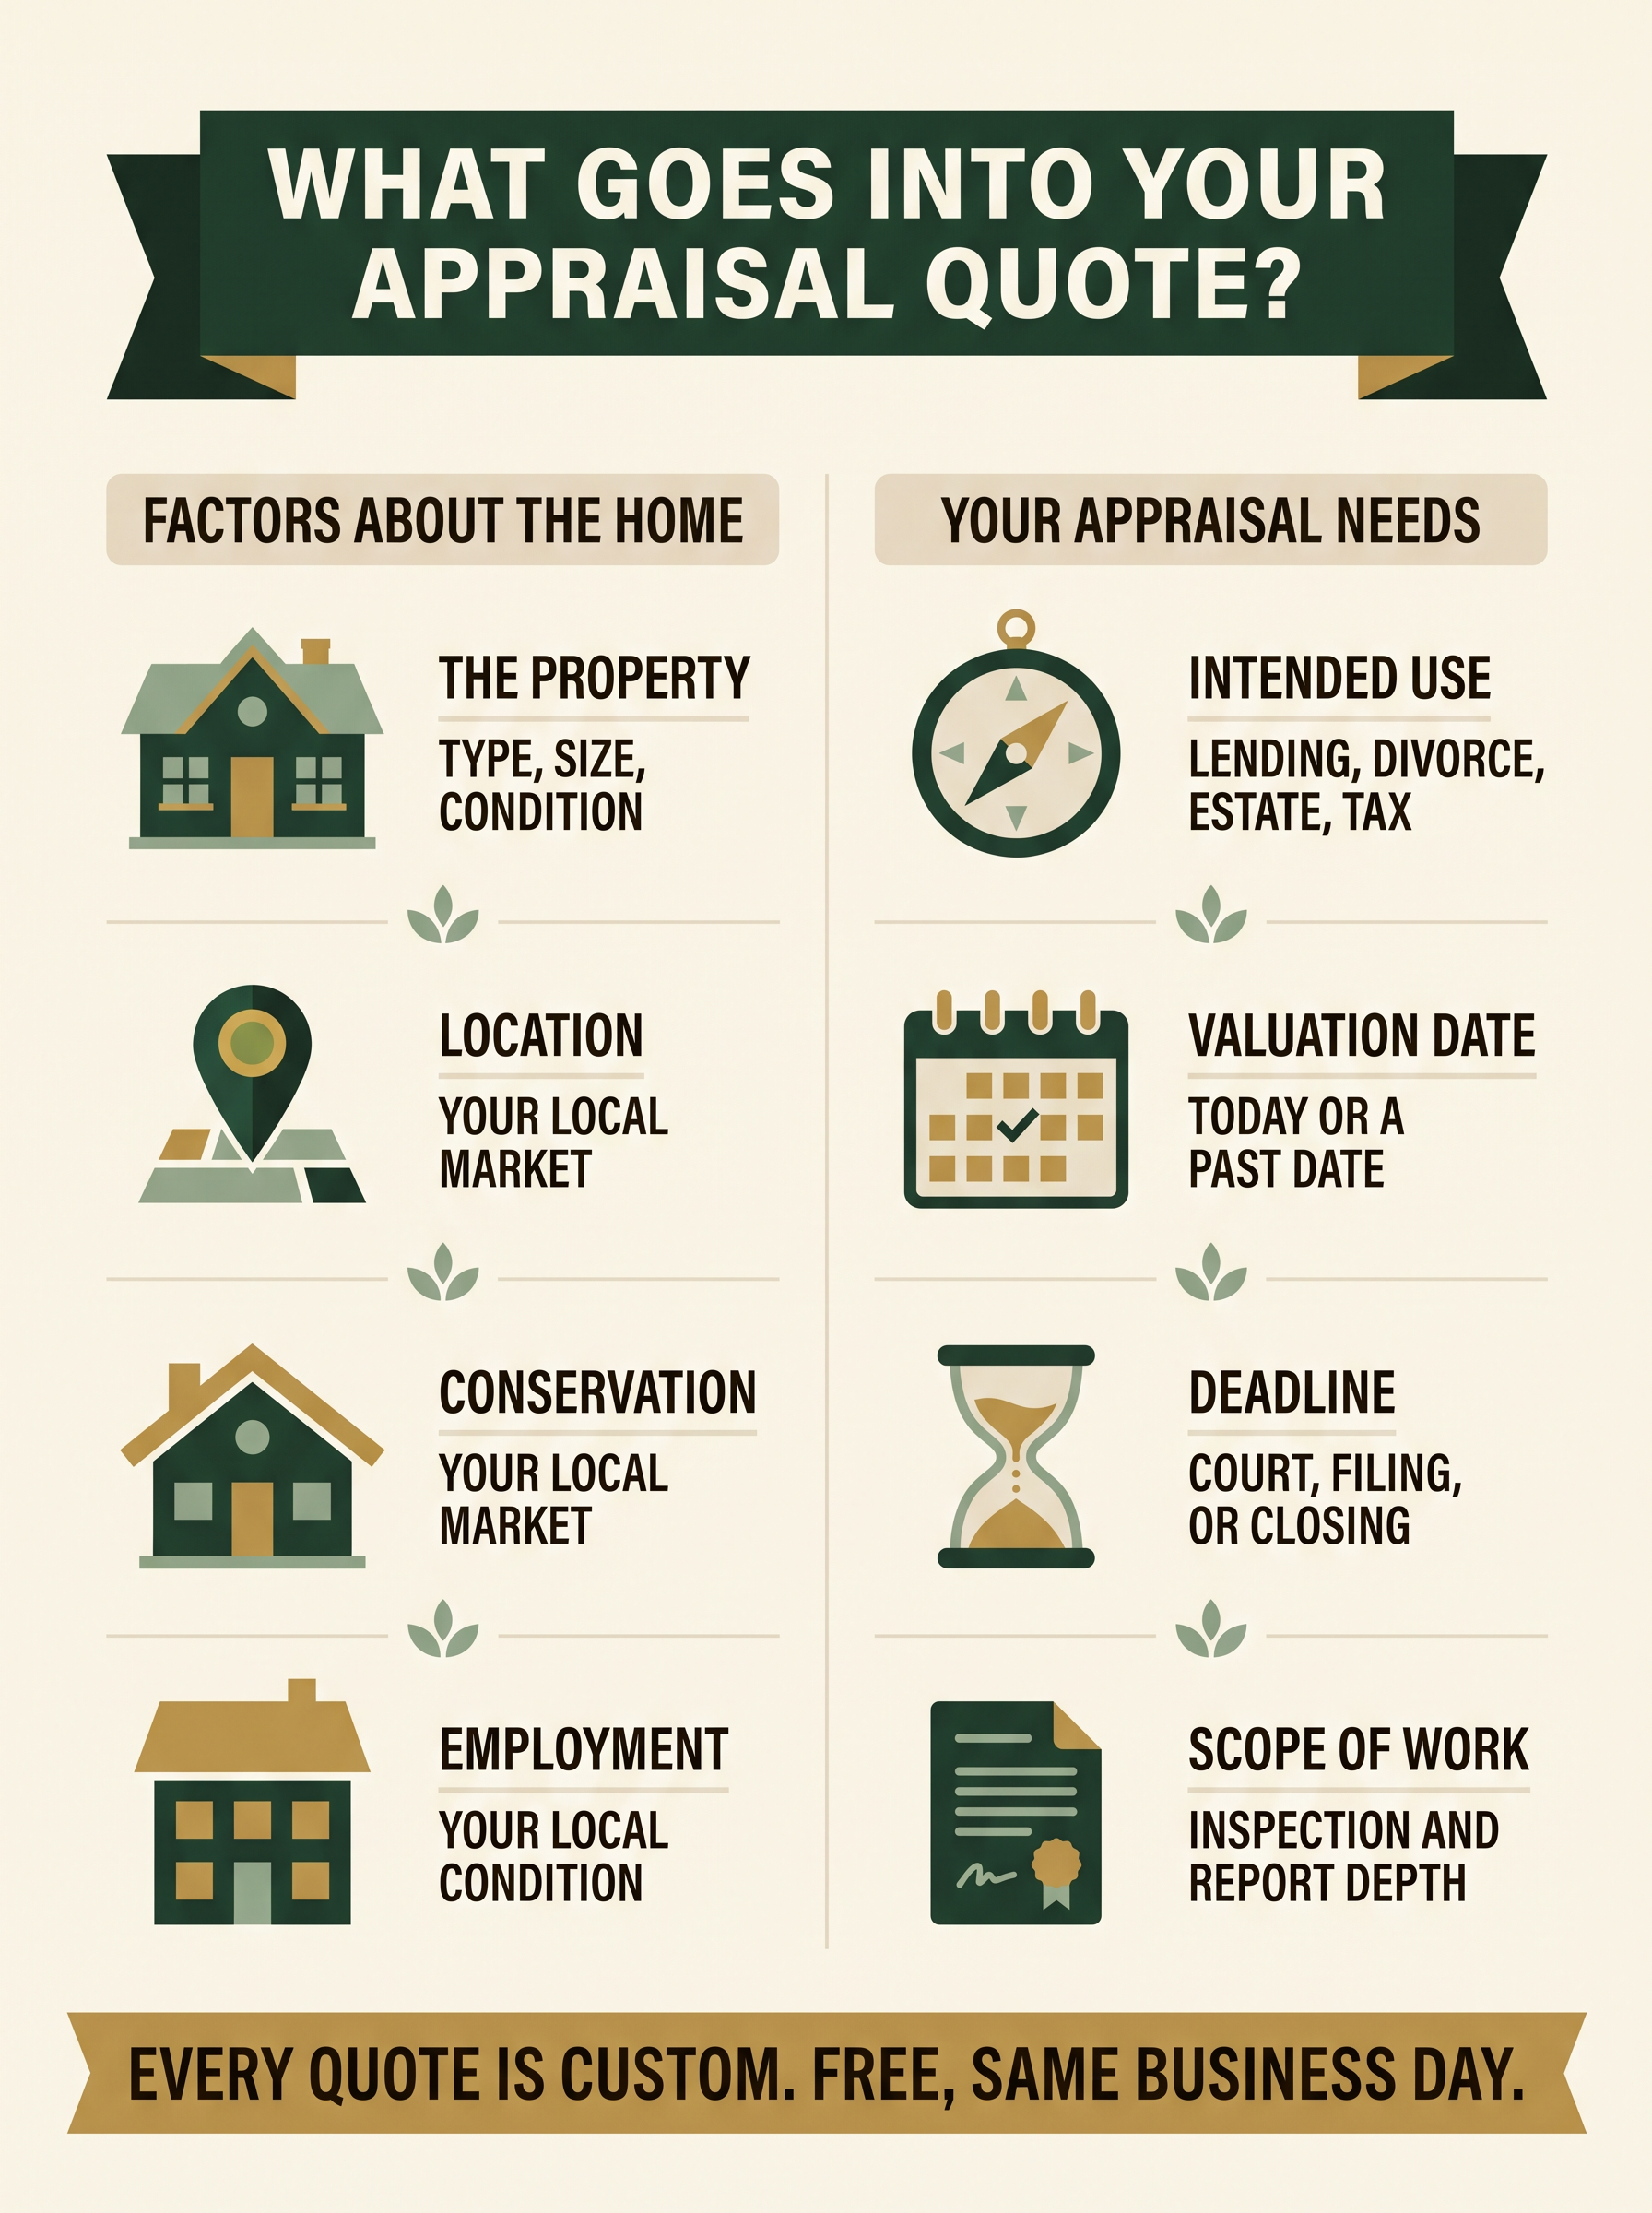
Same-day applies to your quote — the fee and scope. We’re open seven days a week, 8:00 a.m.–5:00 p.m. Central; anything sent after hours is answered the next day.
Mortgage-lending appraisals
Lending assignments are the core of this practice. Green Street Appraisal Services accepts residential appraisal work from banks, credit unions, mortgage lenders, and appraisal management companies across Middle Tennessee and Southern Kentucky — purchase and refinance transactions, portfolio review, and construction-related residential valuations.
Reports are prepared in TOTAL appraisal software and delivered electronically as a PDF or through your designated lender, AMC, or institutional appraisal portal. A typical report is delivered within about three to five business days of the inspection and receipt of all necessary information; expedited service is available for an additional fee depending on location, complexity, and scheduling availability.
If you place recurring residential work or need draw-inspection coverage, there’s a direct professional inquiry path for appraisal-panel consideration and vendor onboarding — you’ll be corresponding with the appraiser, not an intake queue.
Pre-listing appraisals for sellers
Pricing a home is the single biggest decision a seller makes, and it's easy to get wrong in either direction. A pre-listing appraisal gives you an independent number before your home hits the market, so your asking price rests on analysis rather than hope.
Sellers typically request one when comparable sales are scarce, when the home has unusual features or acreage, or when they simply want an impartial check before committing to a listing price. Some sellers also use the appraisal to understand which features of the home carry value in their market.
To scope this assignment, we'll usually ask for the property address, access for an inspection, your expected listing timeline, and a summary of updates or renovations with approximate years completed.
For-sale-by-owner (FSBO) appraisals
Selling without an agent means you don't have a professional pricing your home for you — and an online estimate has never walked through your kitchen. An FSBO appraisal fills that gap with an independent, defensible value you can use to set your price and respond to offers.
FSBO sellers request an appraisal to price with confidence, to show serious buyers that the asking price has support behind it, and to negotiate from documented analysis instead of instinct. It's an appraisal, not a marketing service: we don't set your price for you, but we give you the number to build it around.
Professional measurement & square footage
Here is something most sellers don’t realize until it costs them: the square footage in tax records and old listings usually isn’t a measurement at all. It’s an assessor’s figure that may be years out of date, may count space that shouldn’t be counted, and may miss finished space that should be. Pricing per square foot off a wrong number is one of the easiest ways to leave money on the table — or to set a price the market won’t support.
Measuring the home is part of the appraisal, and it’s done from the appraiser’s side of the table:
- Gross living area measured on site — not copied from tax records or a previous listing
- Finished and unfinished space separated the way the market actually treats them; below-grade area isn’t simply added into the total
- Measured to the ANSI Z765 standard for mortgage-lending assignments — the same standard Fannie Mae and Freddie Mac require of lender appraisals
- A documented figure you can stand behind if a buyer, an agent, or their lender’s appraiser questions it
That last point carries more weight than sellers expect. When your buyer’s lender orders its own appraisal, that appraiser measures the house independently. If your listed square footage doesn’t match theirs, the discrepancy surfaces during financing — the latest and most expensive moment to discover it.
We'll ask for the address, access details, your planned timeline, and any recent improvements. If you've had a prior appraisal, sharing it can help us understand the property's history.
Independent purchase valuations for buyers
A purchase is a negotiation, and the other side has a number in mind. An independent valuation tells you what the market data actually supports before you commit — especially useful in cash purchases, off-market deals, or family transactions where no lender-ordered appraisal will happen.
Buyers request these when they want a check on an asking price, when they're buying without financing, or when they're purchasing from a relative or acquaintance and want the price grounded in something neutral. An appraisal informs your decision; it does not guarantee what a seller will accept or what a future sale will bring.
Helpful details for scoping: the property address, whether you can arrange access, the contract or asking price context, and your decision deadline.
Same-day applies to the quote. A typical residential appraisal report is delivered within about three to five business days of the inspection and receipt of all necessary information.
Independent value evidence for assessment challenges
If you believe your property's assessed value is higher than its market value, an independent appraisal can serve as evidence in an appeal. Assessments are often produced by mass-valuation methods that never examine your specific property; an appraisal analyzes your home individually.
Homeowners typically request tax-appeal support after a reassessment notice, and attorneys or tax representatives sometimes order the appraisal on a client's behalf. An appraisal provides independent support for your position — it does not guarantee that an assessment will be reduced, and the decision always rests with the reviewing authority.
Appeal windows and procedures vary by county, and deadlines can be short. Confirm your county’s deadline with the local assessor or board of equalization before ordering, and consult a tax professional or attorney for guidance on the appeal process itself. Tell us your deadline when you request a quote — rush assignments may be possible depending on location, complexity, and availability.
Valuations for planning, family matters, and personal decisions
Not every appraisal supports a sale. Many of our residential assignments exist to inform a private decision: updating an estate plan, reviewing net worth with a financial planner, informing an insurance conversation, or setting a fair price for a transfer between family members.
These requests come from homeowners, families, and the professionals advising them. Because the report may be shared with an advisor, we'll ask about the intended use and intended users up front so the appraisal is scoped correctly from the start.
If you're dividing property in a divorce, that assignment has its own considerations — impartiality between spouses, retrospective dates, and attorney involvement. See our dedicated divorce appraisals page.
Decision support for hard-to-price properties
Some listings resist easy pricing: unusual homes, large or irregular lots, heavy renovations, or neighborhoods with few recent sales. Agents bring us these properties when a comparative market analysis alone doesn't feel solid enough to build a listing strategy on.
An independent appraisal gives the agent and homeowner a shared, neutral starting point — useful for setting expectations, supporting a pricing conversation with a client, or deciding whether to adjust a listing that isn't moving. We remain independent throughout: the appraisal is our opinion of value, not a number chosen to support a listing goal.
To quote these assignments we'll want the address, what makes the property hard to comp, the timeline, and any prior appraisal or pricing analysis you can share.
Your quote — the fee and scope — generally arrives the same day. Reports typically follow within about three to five business days of the inspection.
Retrospective valuations, where applicable
Some decisions hinge on what a home was worth on a specific past date — the date someone passed away, the date of a separation, or the date a property changed hands. A retrospective appraisal develops an opinion of value as of that earlier effective date, using market data from that period.
These assignments are commonly requested by executors, attorneys, and families settling estates or resolving legal and tax questions. Because the effective date drives the entire analysis, we confirm it — and the reason it matters — before quoting.
For date-of-death valuations and estate work, see our estate, probate & tax page.
Land and improvement allocation, where applicable
Certain assignments call for more than a single total value — they need the value split between the land and the improvements built on it. Allocation questions come up in tax and accounting contexts, insurance conversations, and some planning scenarios.
These requests often come through a homeowner's accountant, tax professional, or financial advisor. Whether an allocation is appropriate, and how it should be used, depends on your situation — we scope the assignment to the question being asked, and we recommend consulting your tax professional about how the results apply to you.
What we may ask you for
You don't need everything on this list to request a quote — but having it handy makes your quote faster and your appraisal smoother.
- The property address
- Access details — who can let us in, and any scheduling constraints
- The purpose of the appraisal and who will use it
- Your deadline or decision date
- Any prior appraisal of the property, if one exists
- A list of updates and renovations, with approximate years completed
Answers for homeowners, sellers, and buyers
How much does a residential appraisal cost?
Will a pre-listing appraisal tell me what my home will sell for?
Do I need to prepare my home before the inspection?
Can an appraisal guarantee my property-tax assessment gets lowered?
Get an independent number you can act on
Tell us about the property and why you need the appraisal. We'll review your request and provide a customized quote.